Equipment Loan Calculator
Enter the equipment price, down payment, rate and term to get the payment, total interest and a payoff schedule; add a trade-in, sales tax, fees or an extra payment if you have them.
Recent
Your last 10 settings, saved only in this browser. Nothing is uploaded.
How to use the Equipment Loan Calculator
- Type the price of the equipment.
- Type the down payment, if you are making one.
- Open More options and type the trade-in credit in dollars, if you are trading in another machine.
- In More options, type the sales tax rate for your area. Rules vary by place, so use the rate you were quoted. If tax should be charged on the price minus the trade-in, tick “Charge tax only on price minus trade-in”.
- In More options, type any fees financed, meaning fees the lender or seller rolls into the loan.
- Type the interest rate (APR, %), which is the annual interest rate.
- Type the loan term and choose years or months.
- In More options, choose Payments: monthly (12 a year) or every 2 weeks (26 a year).
- Optional: type an extra payment each period. It is added to every payment.
- Optional: in More options, type a first payment date as YYYY-MM-DD to see dates in the payment schedule.
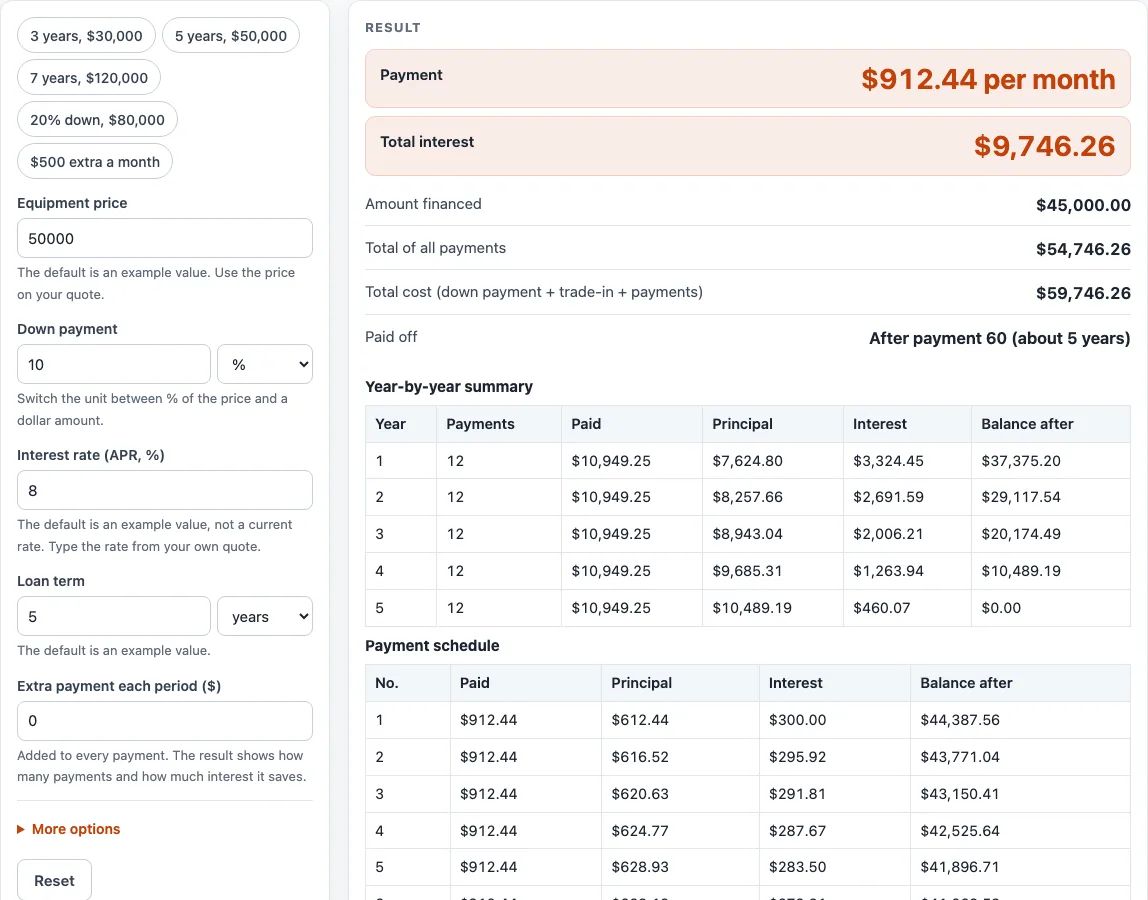
- Read the payment result, then check “Total interest”, “Total of all payments”, and “Total cost”. Scroll to the year-by-year summary table and the payment schedule, which shows the first 120 rows.
- If you typed an extra payment, compare “Time saved by the extra payment” and “Interest saved by the extra payment” with the loan without it.
Change one number at a time, such as the term or the APR, to see how each one affects the payment and the total cost.
How is the monthly payment on an equipment loan calculated?
The payment is found with the standard loan formula: P × i ÷ (1 − (1 + i)^−n). Here P is the amount you borrow, i is the interest rate for each payment period, and n is the total number of payments. The tool uses this same formula, and it matches a textbook example from OpenStax that gives a payment of $973.50.
P is the price, minus the down payment, minus the trade-in, plus sales tax and fees. Sales tax is charged on the full price, or on the price minus the trade-in when that box is ticked. The tax rate is the one you type, because rules differ from place to place.
The interest rate per period is the APR divided by the number of payments per year. For a monthly loan at 6% APR, i is 0.06 ÷ 12, which is 0.005. The number of payments, n, is the term in years multiplied by the payments per year. A 5-year monthly loan has n = 60.
If the APR is 0%, there is no interest, so the payment is simply P divided by n. With the same rate, a longer term lowers each payment but raises the total interest.
How are total interest, total cost, and interest saved worked out?
These totals come from a payment-by-payment schedule. The schedule uses the unrounded payment, while a lender rounds the payment to the cent, so a lender’s figures can differ slightly. Total interest is the total of payments minus the amount borrowed, and total cost is the down payment plus the trade-in plus all payments.
Extra payments are added to every payment in the schedule. The tool then runs the same loan again without the extra payment, so the time saved and the interest saved are the differences between the two runs.
The Payments setting uses plain arithmetic: the periodic rate is the APR divided by 12 for monthly payments or 26 for every two weeks. Some lenders calculate biweekly or odd-period loans in a different way, so a lender’s schedule can differ slightly from this one. The results show what your inputs produce under this method. Check the figures in your loan agreement before you rely on them.
Sources (checked 15 October 2026): openstax.org · openstax.org
Worked examples
| Input | Result |
|---|---|
| $50,000.00 at 8 % for 5 years | $912.44 per month, interest $9,746.26 |
| $50,000.00 at 6.5 % for 3 years | $1,379.21 per month, interest $4,651.38 |
| $50,000.00 at 8 % for 5 years | $912.44 per month, interest $6,871.49 |
Calculated by the tool above; open it with the same values to see each step.
Frequently asked questions
Does this equipment loan calculator include sales tax?
Yes. You type the sales tax rate, and the tool adds the tax to the amount financed. If you tick “Charge tax only on price minus trade-in”, the tax is charged on the price minus the trade-in; otherwise it is charged on the full price.
What is the difference between APR and the periodic rate?
APR is the yearly interest rate. The periodic rate is the APR divided by the number of payments per year, and that smaller rate is applied to each payment.
Why might my lender’s payment differ from this result?
Lenders may round differently, handle fees in another way, or calculate biweekly and odd-period loans differently. Use this result to compare options, then confirm the exact figures with the lender.
What happens if the APR is 0%?
With no interest, the payment is the amount financed divided by the total number of payments. The total interest is zero.
How does an extra payment change the loan?
The extra amount is added to every regular payment, so the loan is paid off sooner. The time saved and interest saved results show how much you would save compared with the same loan without the extra payment.
Is the result financial or tax advice?
No. It is arithmetic on the numbers you type. It does not recommend a loan, a lender, or a tax treatment.
Related tools
- Equipment Depreciation Calculator: use it to estimate how the value of equipment may fall over time.
- Equipment Lease Calculator: use it to compare leasing numbers with a loan.
- Heavy Equipment Loan Calculator: use it when the machine is large and you want a loan calculation set up for that kind of purchase.
- MACRS Depreciation Calculator: use it to run MACRS depreciation on your own figures.
- MACRS Depreciation Table: use it to look up the MACRS percentages table.
- Semi Truck Loan Calculator: use it when the purchase is a semi truck.
- Tractor Loan Calculator: use it when the purchase is a tractor.
- Trailer Loan Calculator: use it when the purchase is a trailer.